All Categories
Featured
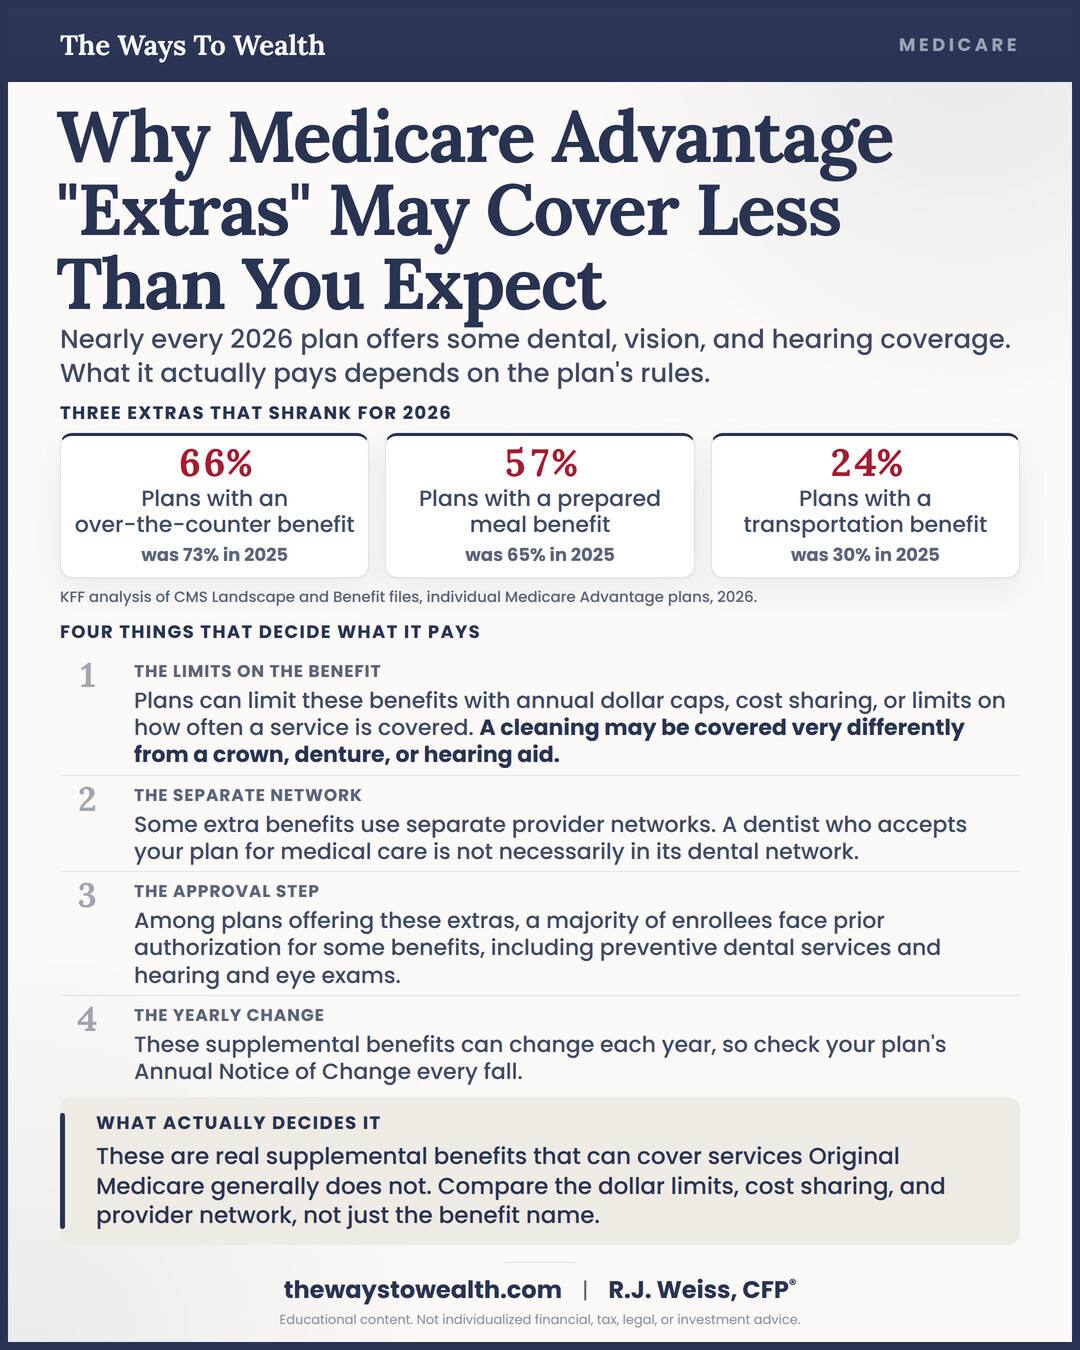
Evaluating 2026 Medicare Advantage Policies
Table of Contents
An HMO insurance strategy is often considered being more cost-effective due to its lower regular monthly premiums and hassle-free due to its requirement that patients need to have a medical care physician to manage their care. A PPO insurance plan is known for its versatility as it permits clients to manage their own care and look for out different providers/specialists without needing a referral.
Similar to general insurance strategies, the 2 main Medicare Benefit strategies are HMO and PPO.While HMO and PPO insurance coverage plans continue to be the most typical choice for patients to pick from, there are a range of other insurance coverage choices. HMO and PPO insurance plans are the 2 most typical healthcare insurance coverage plans in the United States.
A referral is essential for a patient to see other experts that are in-network or out-of-network, and often, getting out-of-network care only takes place in emergency situations. Nevertheless, this plan uses lower monthly premiums for its clients, making it a cost-effective insurance coverage choice. Low monthly premiums. Not as numerous claims to file due to in-network care.

Typically, lower costs for prescriptions. A patient can just see companies within the strategy's network unless they have a referral for an outside expert, or it's an emergency situation. Like an HMO plan, a PPO insurance strategy supplies a patient with a network (described as a "PPO network") of health care service providers and hospitals.
Comparing PPO vs HMO Insurance
This strategy also lets the client coordinate their care and manage which suppliers they would like to see, versus having a primary care doctor. The client has more versatility with which providers they pick to see, whether they're within the plan's network or out-of-network. Many times, there is no need for a recommendation if a patient cares to see an out-of-network professional.
The client is accountable for handling their healthcare, vice a medical care physician supervising. A 'company network' describes the list of doctors, professionals, hospitals, etc that an insurance coverage company contracts to supply medical services to its strategy members. Companies that are 'in-network' describe the health care workers and hospitals that are listed in the strategy.
The expenses associated with an HMO plan include deductibles, which is the amount a client should pay before insurance contributions, and monthly premiums, which is the quantity taken out of a client's income. Normally, the regular monthly premiums taken out with an HMO strategy are lower than a PPO plan's premiums.
Medicare in San DiegoYearly, this led to a $6,869 coverage on individuals and $19,445 coverage on families, revealing a lower month-to-month premium in comparison to a PPO plan type. Most times, the month-to-month premiums are taken out with a PPO plan that is more costly than an HMO strategy's premiums.
Understanding 2026 Medicare Enrollment Rules for Seniors
According to the Kaiser Family Foundation 2018 Health Advantages Survey, all firms utilizing a PPO insurance coverage strategy paid $592 as the month-to-month premium on a private and $1,694 as the monthly premium on a family. Yearly, this caused a $7,149 protection on individuals and $20,324 coverage on households, revealing a higher regular monthly premium in contrast to an HMO plan type.
When attempting to choose which plan is best, there are numerous factors to consider, with a few of the most crucial being versatility, cost performance, and coordination of care. If it's flexibility that is essential, then a PPO insurance coverage plan may be a much better fit for they enable a patient to have more control over which suppliers they see and when, regardless of a referral.
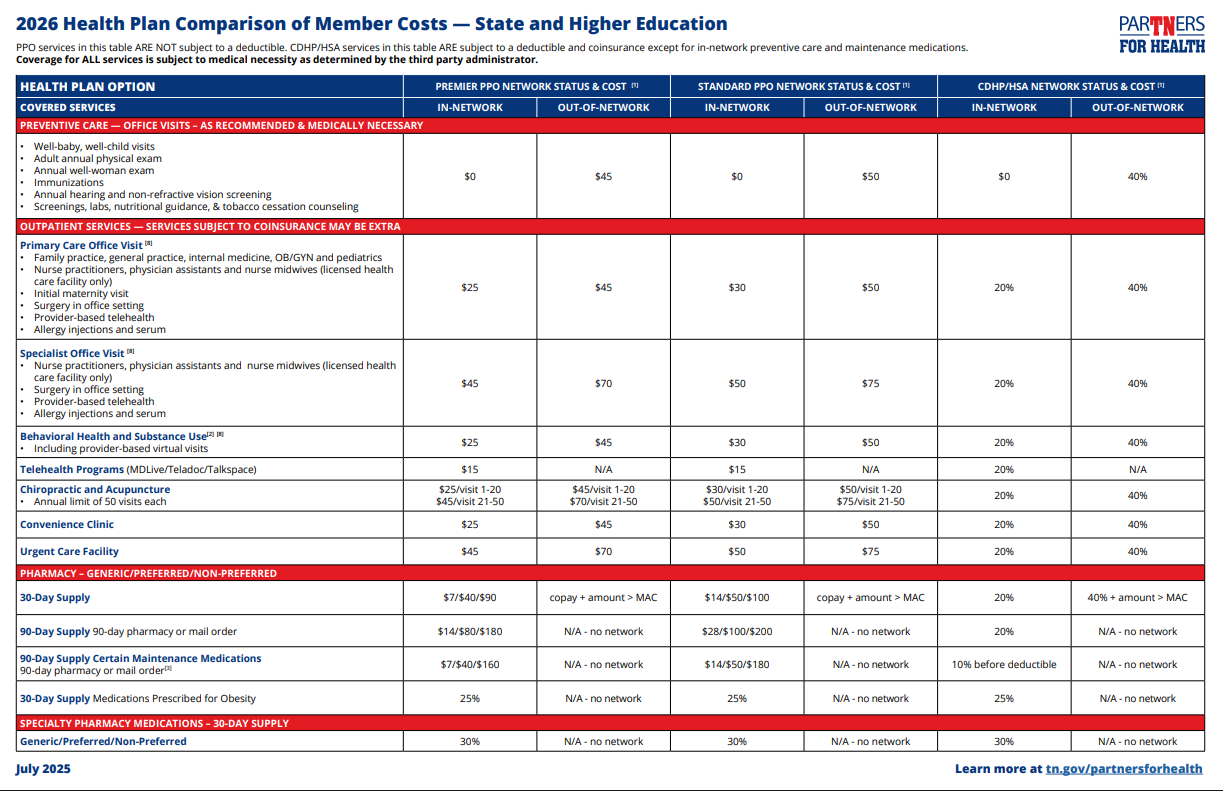
Another advantage to an HMO plan is that it requires a client to have a primary care doctor that coordinates their care for them. This implies that with a PPO insurance plan, the patient will have to manage their own care and manage which providers/specialists they require to go to. In the end, one plan is not considered better than the other.
Health insurance strategies do not cover oral insurance coverage. For more details on obtaining a dental plan, such as a dental HMO plan, 'DHMO plan,' or a dental PPO strategy, 'DPPO strategy,' check out this resource. When an American (who has actually been paying Medicare taxes for a minimum of 10 years) turns 65, they receive the medical insurance strategy referred to as Medicare.

Latest Posts
Life Insurance Strategies for Veteran Families

Selecting Your Optimal 2026 Medicare Advantage Plans
Comparing HMO Network Flexibility versus Monthly Costs